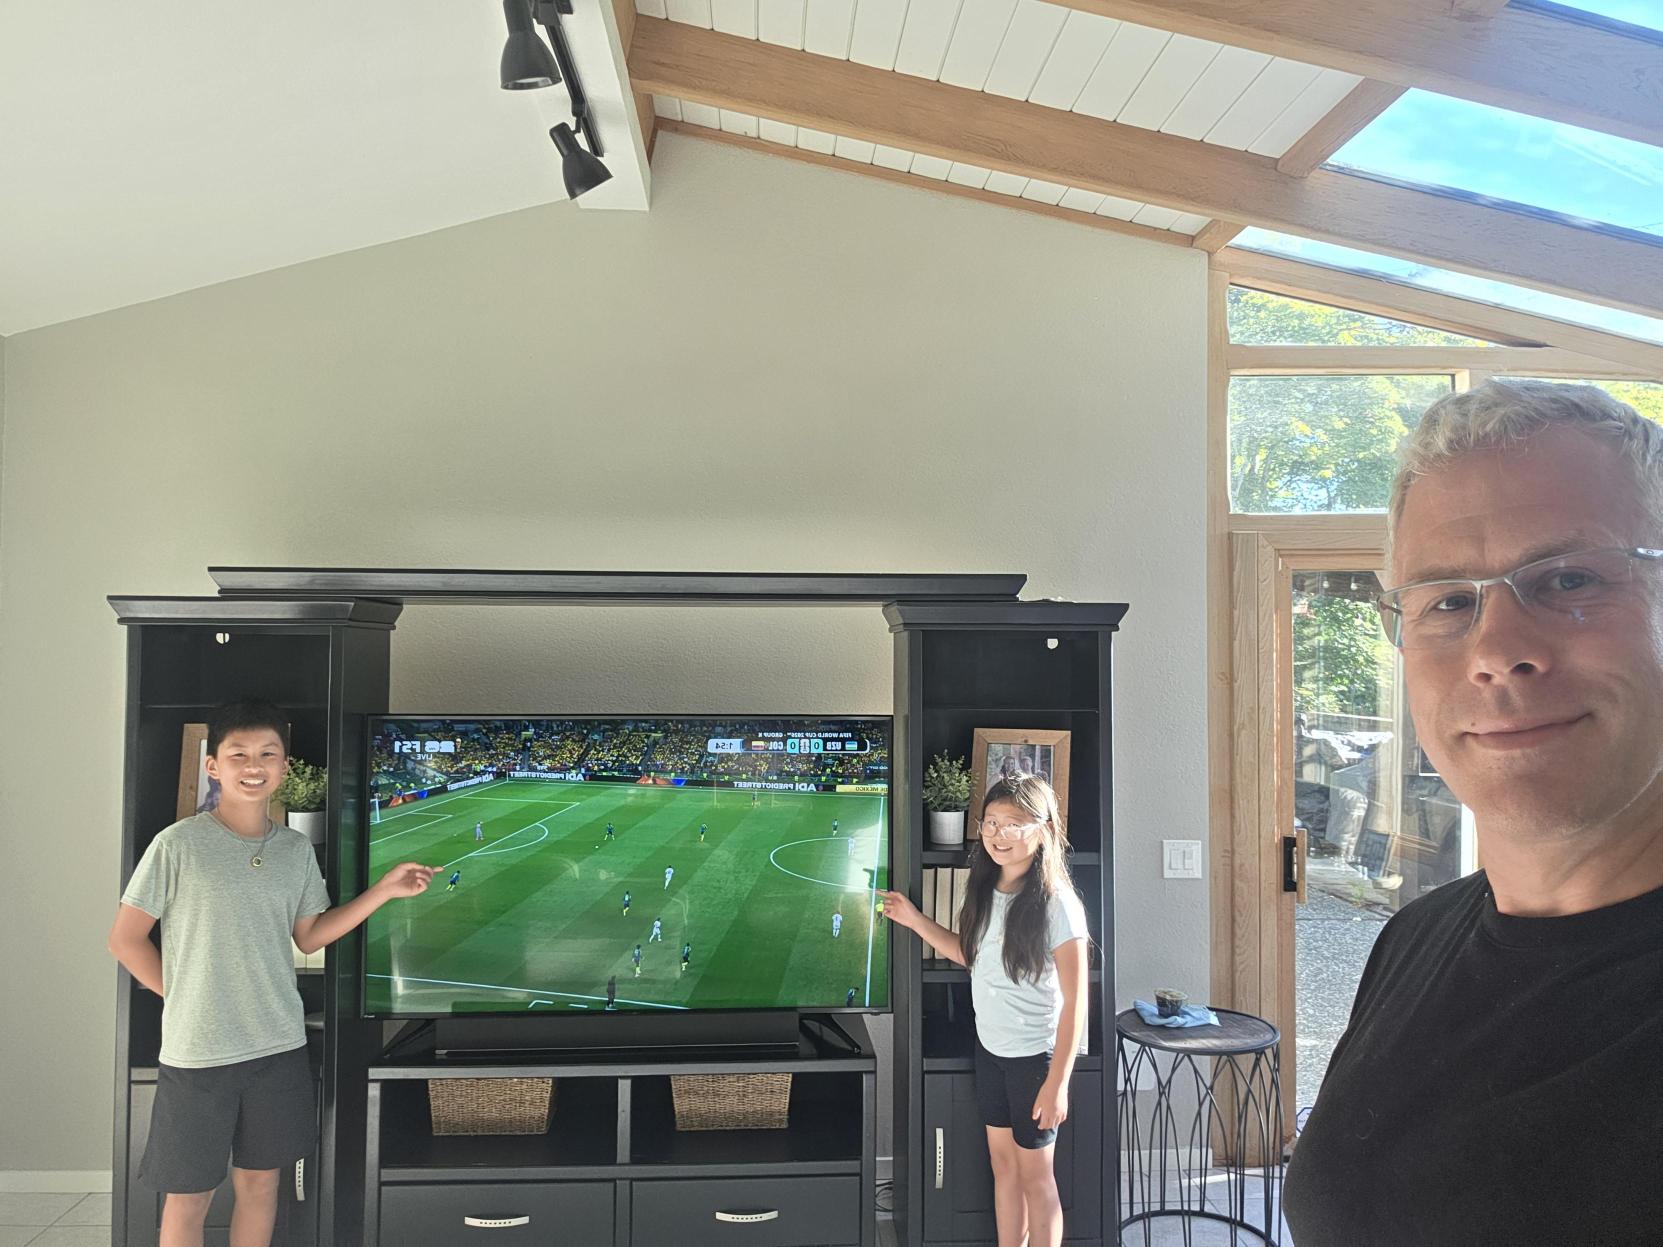
Ahead of tonight’s US World Cup game, we hope you’re as excited to cheer on the team as we are. The Englund family hasn’t traditionally been European “football” fans, but our recent trips to Mazatlan, Mexico to serve with Back2Back have changed that for our family. Our approach to soccer fandom has actually mirrored what worked in the markets this quarter: we’re diversified across teams, cheering for the US, South Korea, Mexico, and Colombia all at once, for various reasons. We’re down to three teams left, but we like our odds better than if we’d only picked one.
That’s a fitting lens for Q2 2026 as well. The quarter showed once again why avoiding concentration matters. Investors who spread exposure across asset classes caught real tailwinds (equities, chip stocks, and emerging markets all had standout quarters) without taking on the full volatility of a concentrated bet. Below, we break down how the major asset classes performed this quarter.
What Happened in June
Q2 was dominated by the on-again, off-again conflict between the US and Iran, and few of us felt its effects more directly than at the gas pump. Escalating tensions and repeated closures of the Strait of Hormuz, the shipping channel carrying much of the world’s oil, pushed crude prices higher early in the quarter, before sentiment swung back and forth between reports of a near-deal and renewed talk of escalation. The two sides ultimately signed an interim agreement in mid-June. Brent crude ended the quarter down 38.4%, though it remains up 19.8% for the year.
Alongside the oil swings, resilient economic data pushed major central banks toward a more hawkish stance, meaning greater openness to raising interest rates. That shift was clearest at the Federal Reserve, where the first meeting under new chair Kevin Warsh came across more hawkish than expected, with half of the officials who submitted projections favoring another rate hike before year-end. US job growth also stayed strong, averaging 188,000 over the three months through May, the highest pace in two years. The European Central Bank delivered its first rate hike since 2023, and the Bank of Japan raised rates as well, even as the yen weakened to its lowest level against the dollar since 1986.
Even with all of that, many asset classes still posted strong results. The S&P 500 returned 15.2% for the quarter, its best showing since the post-pandemic rebound of 2020, and European equities had a similarly strong quarter. Technology and semiconductor stocks saw the biggest gains of all, with the Philadelphia Semiconductor Index (+88.0%) and South Korea’s KOSPI (+67.9%) posting some of their best quarters on record, on optimism about continued demand for advanced chips tied to AI infrastructure. Emerging market equities broadly also had a standout quarter, gaining 24.1% in US dollar terms.
The quarter is a useful reminder of how differently asset classes can behave within the same three months. Oil, gold, silver, and bitcoin all posted meaningful declines as geopolitical tensions eased and central banks leaned hawkish, while equities, chip stocks, and emerging markets moved the opposite direction on many of those same headlines. A portfolio concentrated in any one of these areas would have had a very different quarter than one spread across several. That is the throughline of Q2 2026: not every asset class moved together, and diversification did what it is generally designed to do, smoothing the ride. Correctly picking, in advance, which single team or asset class will come out on top in a given quarter is highly unlikely, no matter how confident the pick.
Wrapping Things Up
No one can know in advance which asset classes will lead or lag in a given quarter, and Q2 2026 was a good example of how quickly sentiment can shift on a handful of headlines. That is exactly why we build portfolios around a long-term plan rather than a single bet. If anything about the current environment has you thinking about your own portfolio or plan, we would love to hear from you.
Data sourced from Deutsche Bank Research, "Early Morning Reid: June and Q2 2026 Performance Review," dated July 1, 2026.

IMPORTANT DISCLOSURE: This article is produced by Ceva Capital LLC dba Ceva Advisors. The information contained in this report is informational and intended solely to provide educational content to our clients and other readers that we find relevant and interesting. Opinions expressed are just that, and are current only as of the date of publication. Nothing in this document should be construed as investment advice; we provide advice on an individualized basis only after understanding your circumstances and needs. The information presented in this newsletter is based on reports from Deutsche Bank and Bloomberg's '5 Things You Need to Know to Start Your Day' series. Data provided comes from sources we believe are reliable, but accuracy is not guaranteed. Discussion of sectors and the performance of region-specific equities and bonds generally refers to market indices. We use the S&P 500 to represent US large-cap; the Wilshire Small Cap to represent US small-cap; the MSCI ACWI ex US to represent international equities; the US 10-year Treasury Yield to represent US Treasuries; the ICE BofA European Government Bond Index to represent European bonds; the ICE BofA US Corporate Index Effective Yield to represent investment-grade bonds; the ICE BofA US High Yield Index Effective Yield to represent high-yield bonds. Indices are unmanaged, are not subject to investment management fees or transaction costs, and it is not possible to invest in an index. Index performance can provide general information about how a particular region or investment has performed, but does not provide information about the performance of Ceva's client portfolios. Actual client performance may differ materially from the index performance discussed. Past performance is not a guarantee of future results. Financial planning is a tool that can help clients consider different current and future scenarios and construct portfolios designed to meet specific goals and address specific risks. Financial planning does not guarantee a positive outcome or prevent loss. It's important to revisit financial plans and the underlying assumptions of those plans regularly, and to make adjustments as needed to respond to changing circumstances.